Guide
At-Fault vs Not-at-Fault Accidents and Your Insurance
How insurers determine fault, what partial fault means, how not-at-fault claims are treated, and why a not-at-fault accident can still cost you.
By Nathan Price · Research Writer
Published · Updated
Answer in brief
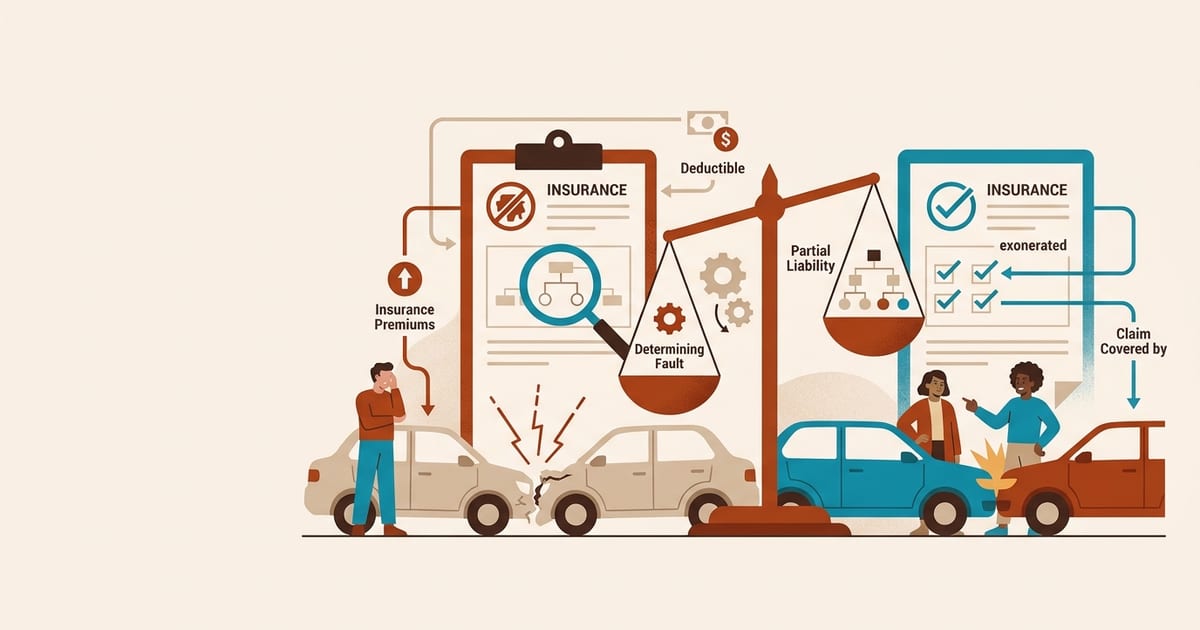
Insurers assign fault using the official crash report, statements, photos and state negligence rules—not the ticket alone. A not-at-fault accident where the other driver is identified usually produces little or no increase and is paid by their insurer. A partial-fault accident (common under comparative-negligence rules) is typically treated as at-fault if you were more than 50% responsible. Not-at-fault claims can still cost you through uninsured-driver situations, hit-and-runs, and insurers that count any claim in frequency scoring.
How fault is decided
- Official crash report and any citations.
- Driver and witness statements.
- Photos, dashcam and physical evidence.
- State negligence rule—pure comparative, modified comparative (50% or 51% bar), or contributory.
- The adjusters' negotiation between the two insurers.
Partial fault
In most states each driver is assigned a percentage. Insurers generally surcharge if you were at least 50% or 51% at fault, and some surcharge any percentage. Ask how your insurer treats partial fault.
Not-at-fault, but still a cost
| Situation | Effect |
|---|---|
| Other driver identified and insured | Usually none; their insurer pays, yours recovers via subrogation |
| Other driver uninsured | Your UM/collision pays; most states bar surcharging, but insurer may count the claim |
| Hit-and-run, no identification | Treated as collision claim; may count in frequency |
| Three or more claims of any kind in 3 years | Frequency surcharge or nonrenewal risk regardless of fault |
Quote finder
Find auto insurance quotes that fit your situation
No-fault states
In no-fault states, your own PIP pays your medical bills regardless of fault, but fault still determines liability for vehicle damage and for surcharges.
Questions & answers
Will my insurance go up if the accident wasn't my fault?
Usually not, if the other driver is identified and insured. Some insurers apply small increases or count the claim.
What if we were both partly at fault?
Most insurers surcharge if you were 50% or more responsible; some surcharge any percentage.
Who decides fault—the crash report or the insurer?
The insurers, using the crash report as one input among several.
Terms used in this guide
- At-fault accident
- A crash for which you are assigned the majority of responsibility; typically surcharged for three to five years.
- Comparative negligence
- A state rule assigning each driver a percentage of fault; insurers typically surcharge at 50% or more.
- Subrogation
- Your insurer recovering what it paid from the at-fault driver's insurer, including your deductible.
- Not-at-fault claim
- A claim where another party is responsible; usually not surcharged, though some insurers count it in frequency.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Background on: No-fault auto insurance — Insurance Information InstituteIndependent researchWhich states use personal injury protection (PIP), how no-fault thresholds work, and reform history including Michigan and Florida.
- Facts + Statistics: Highway safety — Insurance Information InstituteStatistical dataCrash, injury and fatality trends used to explain why liability and injury coverages cost what they do.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- What is covered by a basic auto insurance policy? — Insurance Information InstituteConsumer guidanceDefines bodily injury and property damage liability, MedPay, PIP, uninsured/underinsured motorist, collision, comprehensive and glass coverage.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
- How to file an auto insurance claim — Insurance Information InstituteConsumer guidanceSteps after a crash: document the scene, notify the insurer promptly, understand the adjuster's role.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
- Understanding your insurance deductibles — Insurance Information InstituteConsumer guidanceHow deductibles apply to collision and comprehensive and how raising them lowers premium.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
How Much Car Insurance Goes Up After an Accident
Typical premium increases after an at-fault accident by claim size and state, when the increase appears, and why two insurers can react very differently.
Guide
Should You File a Claim After a Minor Accident?
When to pay out of pocket and when to file—deductible math, surcharge exposure, the other driver's involvement, and the cases where you must report regardless.
Guide
How Long an Accident Affects Your Car Insurance
The three- and five-year lookback periods, how surcharges step down, when the accident drops off your record, and how state rules differ.